Top 5 Wind Turbine Manufacturers Ranked By New Capacity
Top wind turbine manufacturers ranked by 2025 new wind capacity installed using GWEC data. Goldwind leads with 29.7 GW, ahead of Envision worldwide.

Suraj Kadam
Published •13 min read
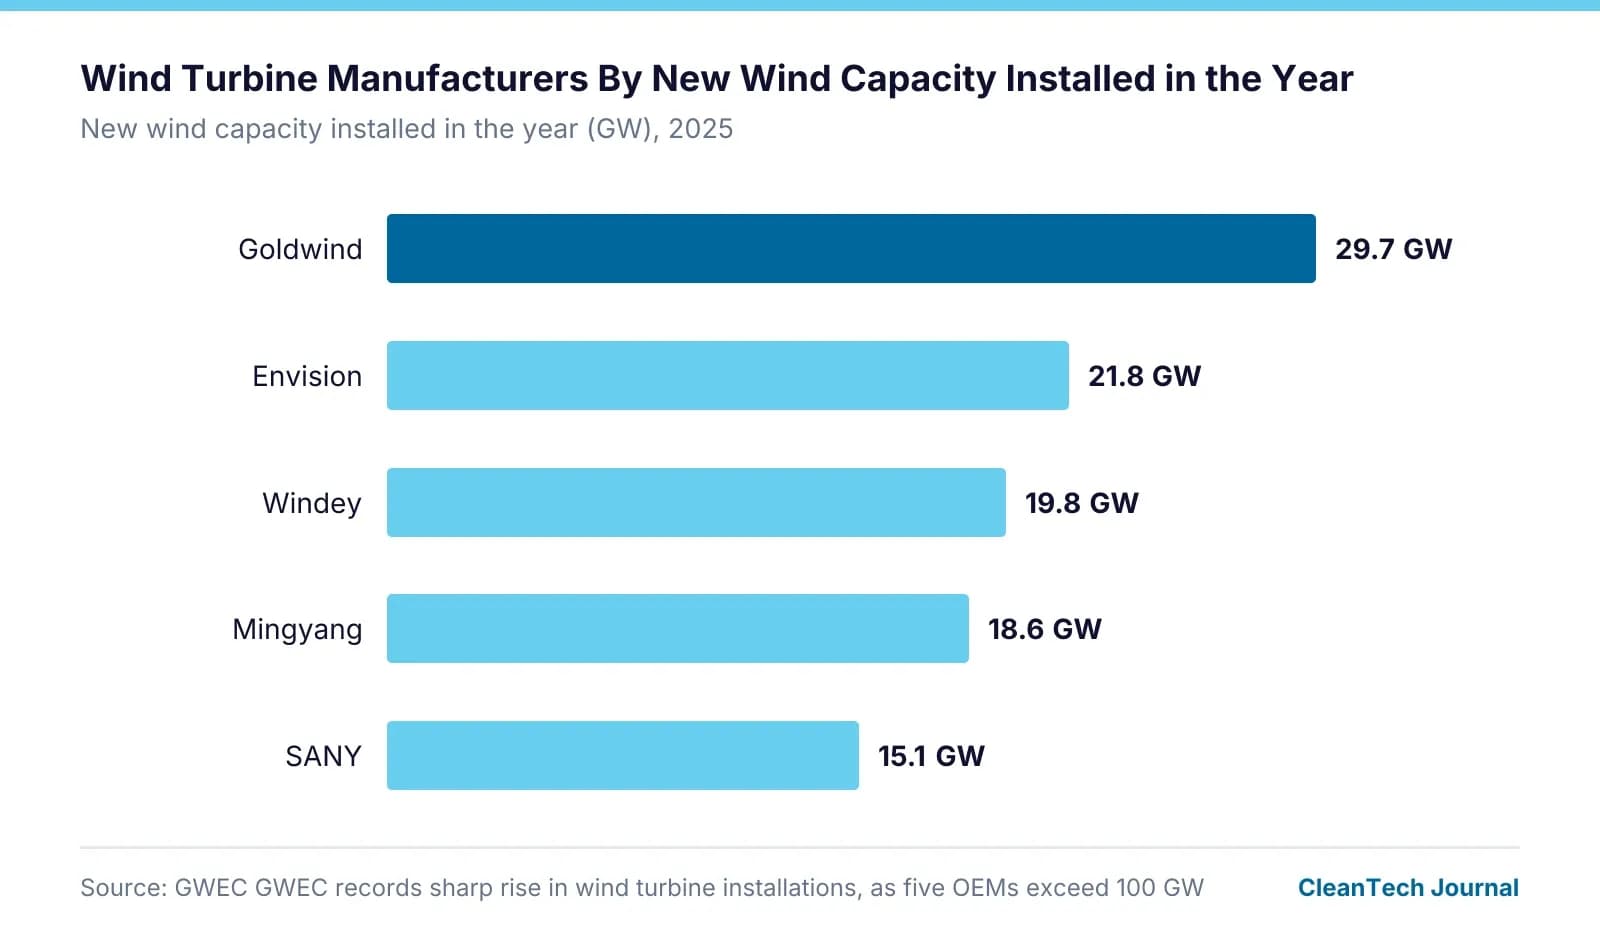
These wind turbine manufacturers are ranked by new wind capacity installed in 2025, using data from GWEC's Global Wind Market Development Supply Side Data Report. GWEC said the global top five by annual installed capacity were all Chinese OEMs for the first time.
Goldwind leads the ranking with 29.7 GW after installing the highest volume last year. Envision, Windey, Mingyang and SANY follow, highlighting how much 2025 activity was concentrated among the leading suppliers.
Wind Turbine Manufacturers Ranked By New Wind Capacity Installed in the Year
Rank | Wind Turbine Manufacturer | New wind capacity installed in the year (GW) |
|---|---|---|
1 | Goldwind | 29.7 |
2 | Envision | 21.8 |
3 | Windey | 19.8 |
4 | Mingyang | 18.6 |
5 | SANY | 15.1 |
How We Ranked These 5 Wind Turbine Manufacturers
- Ranked by: new wind capacity installed in the year (GW), 2025 data. This is the only measure used for the order.
- Data source: GWEC GWEC records sharp rise in wind turbine installations, as five OEMs exceed 100 GW, retrieved 2026-11-07.
- Included: Turbine makers (OEMs) by capacity commissioned worldwide in the latest full year, onshore and offshore.
- Excluded: Orders not yet installed.
- Ties: none in this list. If two entries had the same figure, cumulative installed capacity would decide.
- Figures: reported exactly as published by the source. CleanTech Journal does not estimate or adjust them; comparisons between entries are our own calculation from these figures.
1. Goldwind: 29.7 GW
Goldwind tops GWEC's 2025 ranking with 29.7 GW of new wind capacity installed, the highest volume recorded by any OEM last year. It finished 7.9 GW ahead of Envision, giving it the largest lead between any two adjacent entries in this top five. GWEC said the five leading suppliers by 2025 installed capacity were all Chinese companies for the first time, with most of their installations in China. Beyond the annual ranking, Goldwind also moved into second place globally for cumulative installations in 2025 at 163 GW. GWEC further identified Goldwind as the third most globalized supplier, with installations in 23 countries during 2025.
2. Envision: 21.8 GW
Envision ranks second after installing 21.8 GW in 2025. That put it 7.9 GW behind Goldwind but 2.0 GW ahead of Windey, placing it in the middle of a tightly grouped section of the ranking. GWEC noted that Envision became the latest manufacturer to join the 100+ GW club in cumulative installations, reaching 103 GW by the end of 2025. It also appeared in GWEC's separate ranking for installations outside mainland China, where Envision placed fifth with 4.2 GW. Like the rest of the top five, Envision is one of the Chinese OEMs whose 2025 installed volumes were mainly in its home market.
3. Windey: 19.8 GW
Windey takes third place with 19.8 GW of new wind capacity installed in 2025. It trailed Envision by 2.0 GW and stayed 1.2 GW ahead of Mingyang, making this one of the closest gaps in the ranking. GWEC said 2025 was the first year that the global top five suppliers by annual installed capacity were all Chinese companies. The report added that these leading volumes were mainly installed in China, reflecting the strength of domestic demand there.
4. Mingyang: 18.6 GW
Mingyang ranks fourth with 18.6 GW installed in 2025. The gap to Windey above it was just 1.2 GW, while SANY sat 3.5 GW behind. GWEC's data shows how closely clustered the middle of the ranking was, even as all five leaders were Chinese OEMs. The report linked that outcome to strong demand in China, where more than 130 GW of new onshore and offshore wind capacity was mechanically installed in 2025 and 120 GW was commissioned.
5. SANY: 15.1 GW
SANY rounds out the top five with 15.1 GW of new wind capacity installed in 2025. It finished 3.5 GW behind Mingyang, and the overall spread from first-place Goldwind to fifth-place SANY was 14.6 GW. SANY's place completed an all-Chinese top five in GWEC's annual installed-capacity ranking. In the wider market context described by GWEC, 18,291 turbine units were installed in China in 2025, equal to 67% of the global market.
The Top Three Installed 71.3 GW, Or 67.9% Of The Top Five Total
Together, the five manufacturers installed 105.0 GW in 2025. Goldwind alone accounted for 28.3% of that combined figure, while Envision and Windey added 20.8% and 18.9%. The ranking is especially tight from second to fourth place, with only 3.2 GW separating Envision's 21.8 GW from Mingyang's 18.6 GW.
The widest adjacent gap is between first and second, at 7.9 GW. By contrast, Windey and Mingyang are separated by just 1.2 GW, the smallest gap on the list. From Goldwind at 29.7 GW to SANY at 15.1 GW, the full spread across the ranking is 14.6 GW.
SOURCES
Written by
Suraj Kadam
Suraj Kadam is a journalist and Chief Editor of CleanTech Journal, a knowledge and media platform covering clean technology, solar energy, and renewable energy. He reports on emerging technologies, industry developments, policy trends, and innovations shaping the global clean energy transition. Through his editorial work, Suraj aims to make complex clean technology topics accessible to industry professionals, researchers, policymakers, and readers interested in sustainable energy. His work focuses on delivering insightful, informative, and engaging coverage of the evolving renewable energy landscape.